Singlife CareShield Standard and Plus
Two government-approved supplement plans that boost your CareShield Life or ElderShield payouts so that you can get the care you need during unexpected events in life.

Two government-approved supplement plans that boost your CareShield Life or ElderShield payouts so that you can get the care you need during unexpected events in life.
Footnotes
All ages mentioned refer to age next birthday (ANB).
* Activities of Daily Living (ADLs) refer to washing, toileting, feeding, dressing, transferring around and walking or moving around.
1. You are unable to perform at least two (for Singlife CareShield Plus) or three (for Singlife CareShield Standard) of the six Activities of Daily Living (ADLs).
2. Add-on Benefit payouts start when you're unable to perform 2 ADLs for Singlife CareShield Standard and 1 ADL for Singlife CareShield Plus.
3. There are two ways to pay for a limited time; the later of the two options will apply. The two ways are:
a) The Life Assured may pay up to the policy anniversary after they turn 68
b) The Life Assured may pay for 20 years from entry age (if Life Assured joins at age 49 or older)
4. MediSave use is applicable to an amount of up to S$600, per calendar year, per life assured. Premiums exceeding this limit will have to be paid in cash. If there are insufficient funds in the designated MediSave account, cash payment will be required for the difference.
5. The monthly benefit refers to the monthly payout when the Life Assured suffers from a Severe Disability, as defined in the plan.
6. The Life Assured may receive an additional 20% of their monthly benefit - for up to 36 months - while they're receiving their monthly benefit or rehabilitation benefit.
7. The Life Assured may receive an additional 60% of their monthly benefit - for up to 12 months - while they're receiving their monthly benefit or rehabilitation benefit.
8. A lump sum benefit will be payable if the Life Assured dies due to any accident or sickness while receiving either the Severe Disability Benefit or the Rehabilitation Benefit. The Death Benefit will amount to 3 times of the last paid Severe Disability Benefit or the Rehabilitation Benefit, whichever is applicable.
9. The policyholder may exercise this option, without providing further evidence of insurability at any of the following life stage events, when the Life Assured:
a) purchases a property;
b) marries, divorces or is widowed;
c) becomes a parent by having a newborn child or by adopting a child below 19 years old
d) salary increases by 50% or more from application;
e) completes a skills development course of at least six months;
f) purchases a new individual life insurance policy or a Supplementary Benefit from us, with full underwriting at standard terms; or
g) spouse suffers a Severe Disability (with the inability to perform at least three of the six ADLs) or dies.
This option allows the policyholder to increase the policy's monthly benefit with extra premium payable. The total monthly benefit that can be increased under this option is limited to 50% of the policy’s initial monthly benefit, as agreed at policy inception or at the date this option is exercised – whichever is lower. This option is extended to standard life only. Please refer to the Product Summary for more details.
Both plans offer enhanced support for severe disabilities in addition to the existing government schemes, so you can have better assurance for you and your loved ones.
Buy Now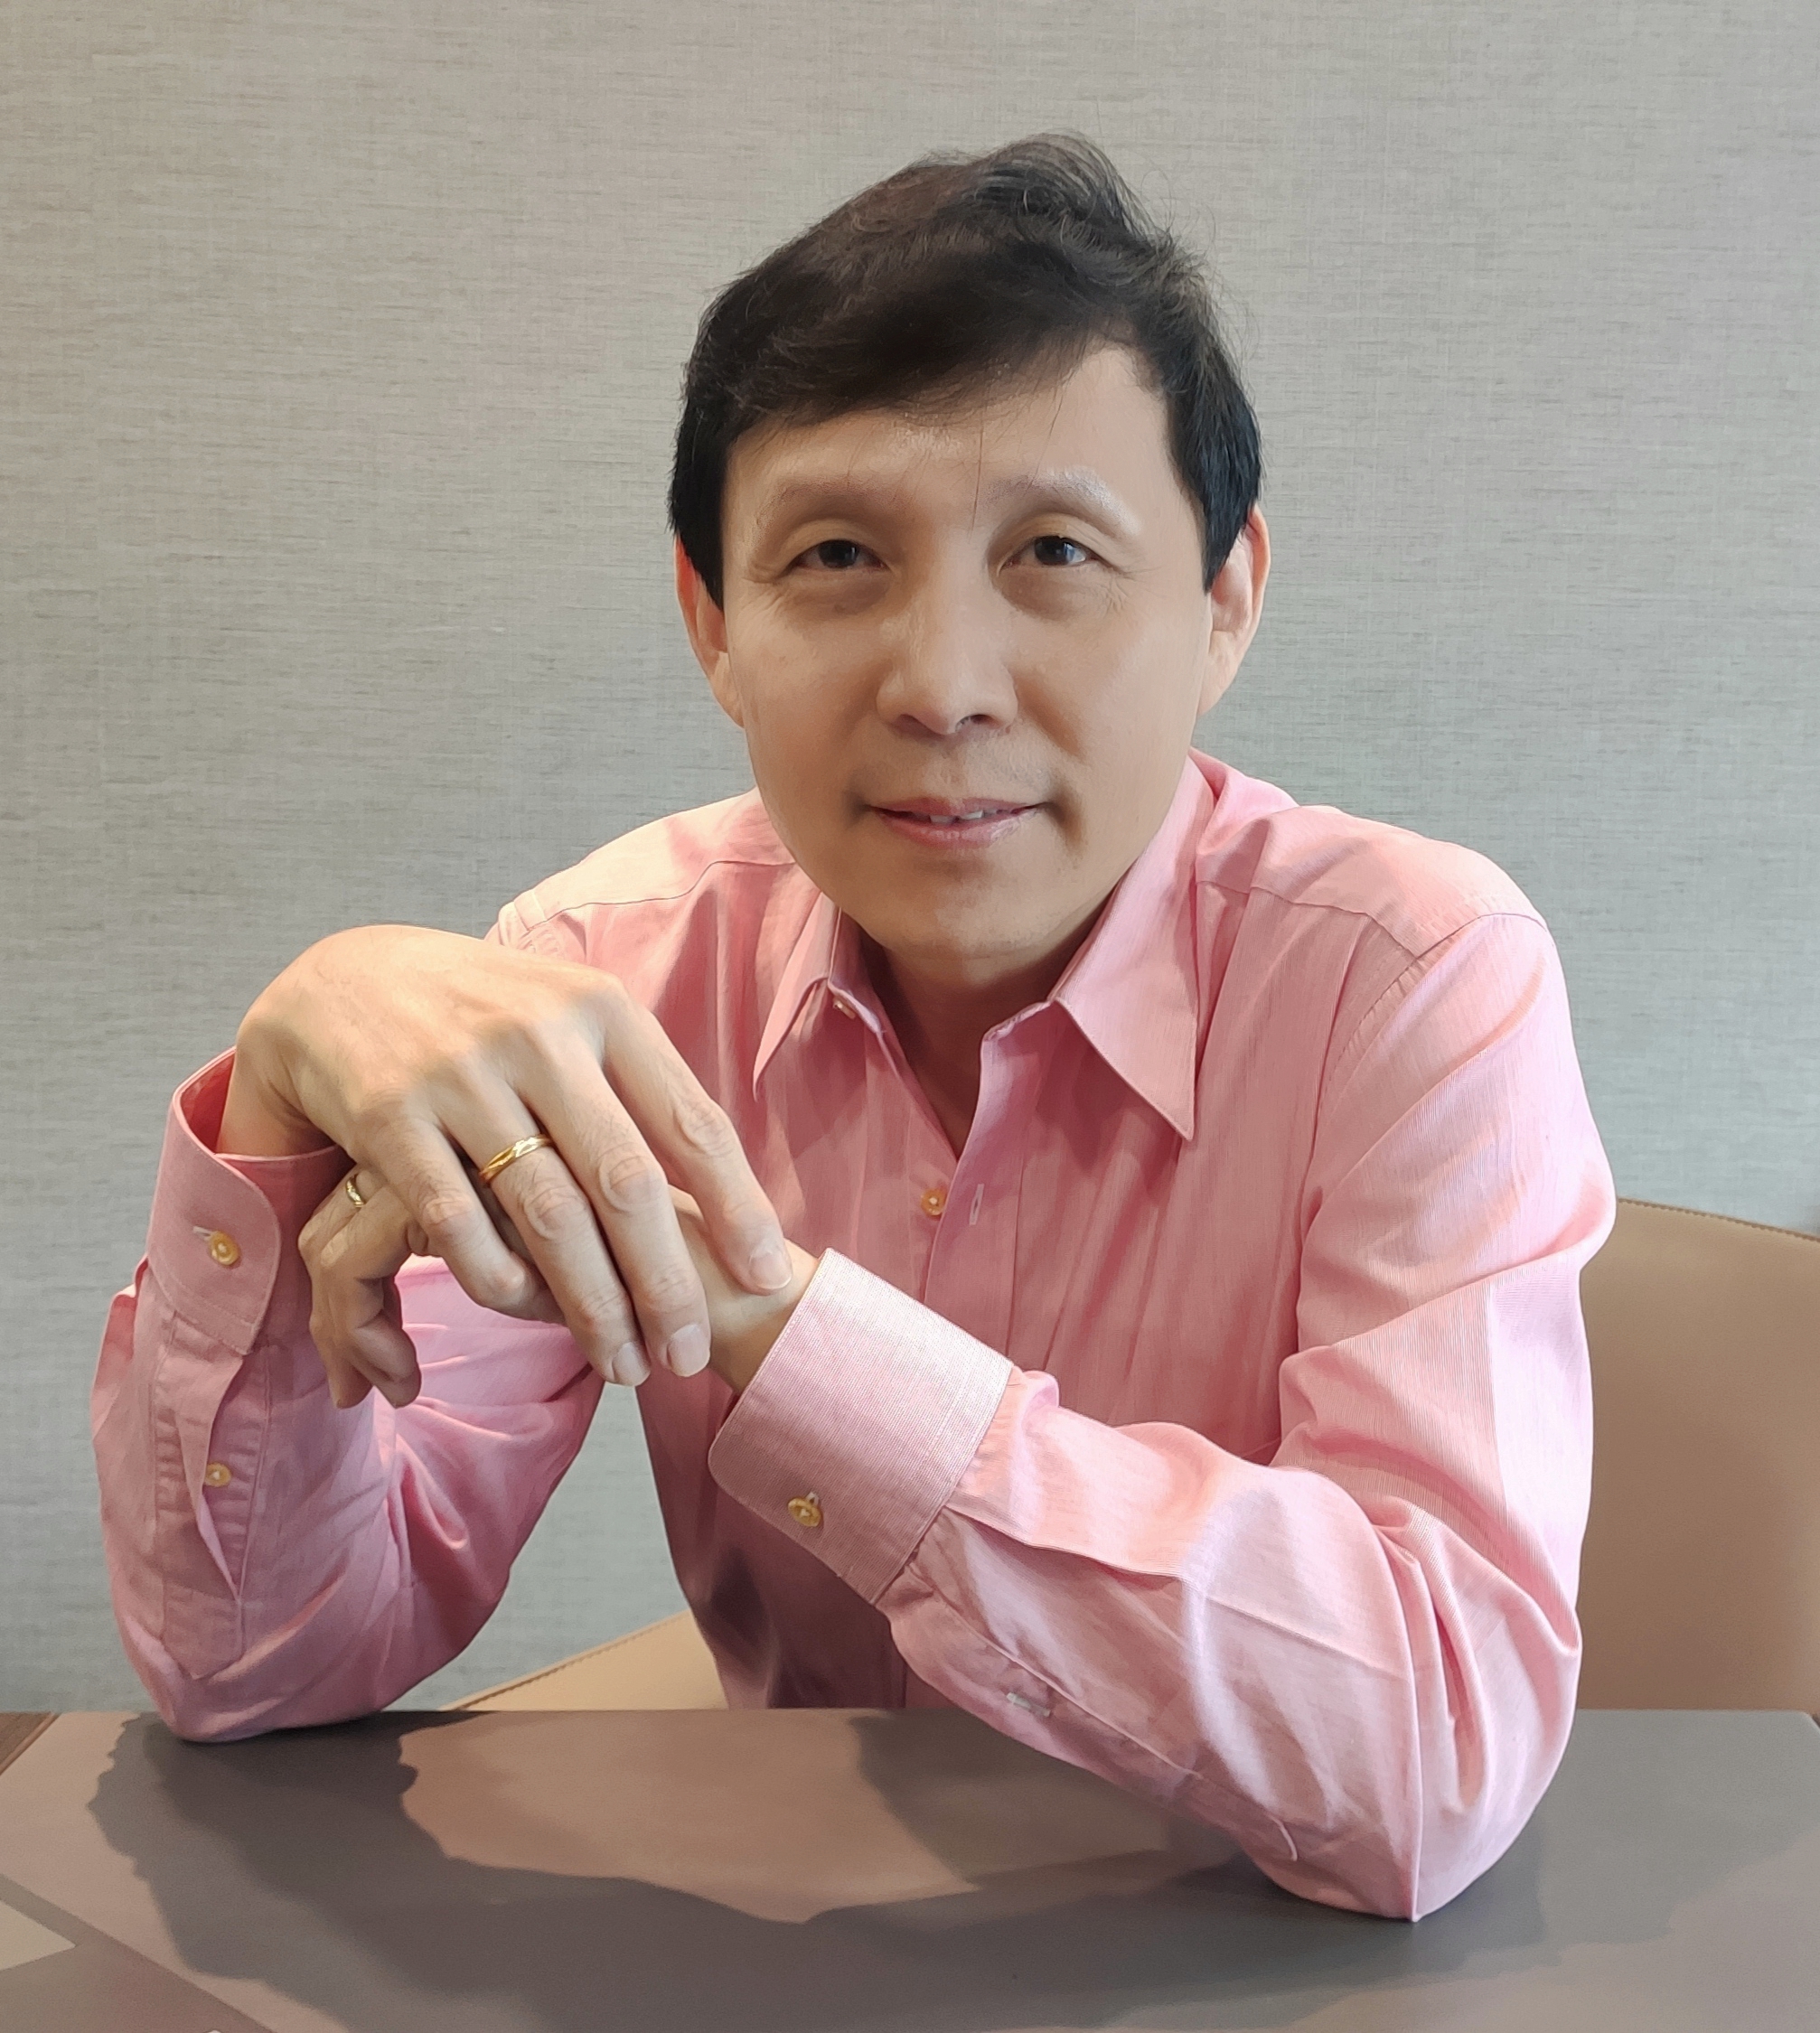

BUSINESS & WEALTH SUCCESSION | ONE TRUSTED ADVISER, ONE-STOP HOLISTIC SOLUTIONS FOR CONTINUITY BEYOND THE FOUNDER
ONE TRUSTED ADVISORY RELATIONSHIP. ONE HOLISTIC PLAN. BROAD SOLUTION ACCESS.
Sofan Tan
Generational Wealth Architect™ |
Certified Estate Planner |
AEPP® | AWP | BBA |
20+ Years in Wealth Management |
Consultant, Financial Alliance Pte Ltd
For founders and high-net-worth families, privacy, time and coordination matter.
I provide holistic planning advisory across business succession, wealth succession, investments, protection, estate planning and intergenerational wealth transfer, guided by TWG™ OS.
Financial Alliance provides the one-stop solutions platform and implementation support.
Instead of seeking several disconnected advisers and providers, you work through one primary advisory relationship and one coordinated planning process.
This reduces fragmented advice, duplicated fact-finding, repeated KYC processes and unnecessary sharing of sensitive family and financial information.
Your business interests, family needs, personal wealth, protection arrangements and succession objectives stay connected to the same plan.
PREPARING THE ASSETS FOR THE NEXT GENERATION, AND THE NEXT GENERATION FOR THE ASSETS
Many founders have an investment plan, insurance policies, a will, trust arrangements or business agreements.
Yet these arrangements often operate separately.
Gaps emerge when ownership, leadership, family roles, estate liquidity and decision authority do not work together.
A succession plan identifies who takes over the business.
A wealth succession plan addresses how family wealth, responsibility and decision-making pass across generations.
An estate plan determines how assets transfer during incapacity or death.
Insurance provides protection and liquidity during critical events.
Investment planning supports capital preservation, growth and future income needs.
My role is to connect these areas through one holistic wealth plan.
WHO I HELP
I work with:
WHAT I HELP YOU ADDRESS
BUSINESS SUCCESSION PLANNING
Clarify the future ownership, leadership and direction of your business.
The planning process addresses founder dependency, successor selection, leadership readiness, ownership transfer, funding requirements and contingency arrangements.
WEALTH SUCCESSION PLANNING
Coordinate the transfer of personal and family wealth with the transfer of responsibility.
This includes beneficiary priorities, liquidity needs, decision roles, family expectations and successor preparation.
HOLISTIC WEALTH PLANNING
Connect your investments, insurance, retirement needs, business interests, estate arrangements and legacy objectives.
Your plan reflects your financial position, family circumstances, liquidity needs, risk capacity, values and long-term priorities.
ESTATE AND LEGACY PLANNING
Review how your assets would be managed and distributed during incapacity or death.
Planning areas include wills, trusts, nominations, lasting powers of attorney, estate liquidity and beneficiary arrangements, supported by appropriate legal and professional specialists.
WEALTH PROTECTION AND INVESTMENT PLANNING
Align protection and investment decisions with your family responsibilities, business exposure and long-term objectives.
The focus stays on protecting capital, managing risk and supporting responsible wealth stewardship.
MY GOVERNANCE PERSPECTIVE
My advisory approach is guided by Total Wealth Governance™ and TWG™ OS.
TWG™ OS connects four forms of family capital:
FINANCIAL CAPITAL
Assets, structures and liquidity.
HUMAN CAPITAL
Capability, character and accountability.
SOCIAL CAPITAL
Trust, relationships and reputation.
DECISION CAPITAL™
The family’s structured capacity to make unified, values-aligned decisions across the Four Capitals and across generations.
This governance perspective aligns wealth structures with people, values and decision capability.
Governance directs.
Succession prepares.
Continuity preserves.
THE FINANCIAL ALLIANCE ADVANTAGE
I provide the holistic planning advisory.
Financial Alliance provides access to a comprehensive range of financial services, solutions and professional resources.
This one-stop approach supports coordinated planning across investments, insurance, estate planning and business succession.
You gain one central planning relationship instead of managing separate conversations without a common direction.
Planning begins with your purpose, priorities and risks. Solutions follow only after the overall strategy becomes clear.
WHAT YOU RECEIVE
CLARITY
A clear view of your priorities, planning gaps and next actions.
PRIVACY
Fewer disconnected conversations, reduced duplication and more controlled sharing of sensitive information.
COORDINATION
A connected approach across business succession, wealth succession, investments, insurance and estate planning.
PROTECTION
Planning for business disruption, incapacity, premature death, estate liquidity and financial risks.
CONTINUITY
A structured plan supporting the transfer of wealth, responsibility, values and decision capability across generations.
MY PROFESSIONAL FOUNDATION
I hold a Bachelor of Business Administration and professional qualifications as a Certified Estate Planner, Associate Estate Planning Practitioner and Associate Wealth Planner.
My work draws on more than 20 years of wealth-management and advisory experience.
As a Consultant with Financial Alliance Pte Ltd, I combine holistic planning advisory with access to the firm’s broad solutions platform and specialist resources.
MY PHILOSOPHY
Wealth is a tool, not a destination.
Purpose before products.
Clarity before complexity.
Prepare the family before transferring the wealth.
Govern your wealth. Guard your values. Grow your legacy.
START A PRIVATE CONVERSATION
If you are preparing for business succession, retirement or an intergenerational wealth transfer, a private strategy conversation will help identify whether your business, family and wealth plans work together.
Email: sofantan@fapl.sg
LinkedIn: www.linkedin.com/in/sofantan-cep